Global payroll and retirement compliance are connected, but they are not the same function. A payroll provider may calculate pay, apply deductions and transmit contribution data. That does not automatically mean it designs the retirement plan, determines legal eligibility, satisfies every disclosure requirement or confirms that the arrangement works in each country.
Employers create risk when they assume “payroll handled it” without documenting the provider’s scope and the responsibilities that remain with the employer, plan sponsor, administrator, pension provider and local advisers. This guide explains that boundary and the controls needed to connect payroll with international retirement benefits.
What Global Payroll Usually Covers
The exact service depends on the contract, country and operating model. Common payroll activities include:
- Maintaining payroll records and calculating gross-to-net pay
- Applying configured deductions and employer contributions
- Supporting local wage, tax and social-contribution reporting
- Producing payroll journals, employee statements and payment files
- Transmitting approved data to benefit or pension providers
Those activities are essential, but they operate from configured rules and source data. Payroll cannot compensate for an undefined plan, incorrect eligibility record or missing country analysis.
What Payroll Does Not Automatically Resolve
Unless the provider has explicitly contracted to perform them, do not assume payroll owns:
- International pension plan design and governance
- Whether an employee must participate in a local mandatory scheme
- Whether a supplemental or international arrangement receives a particular tax treatment
- Plan documents, participant disclosures and investment governance
- Cross-border portability, vesting or withdrawal rules
- Legal analysis after an employee changes country or employment status
- Oversight of pension providers, custodians and administrators
The OECD Core Principles of Private Pension Regulation emphasize clear objectives, governance, member protection, controls and explicit responsibilities. Outsourcing a transaction does not remove the need for that governance.
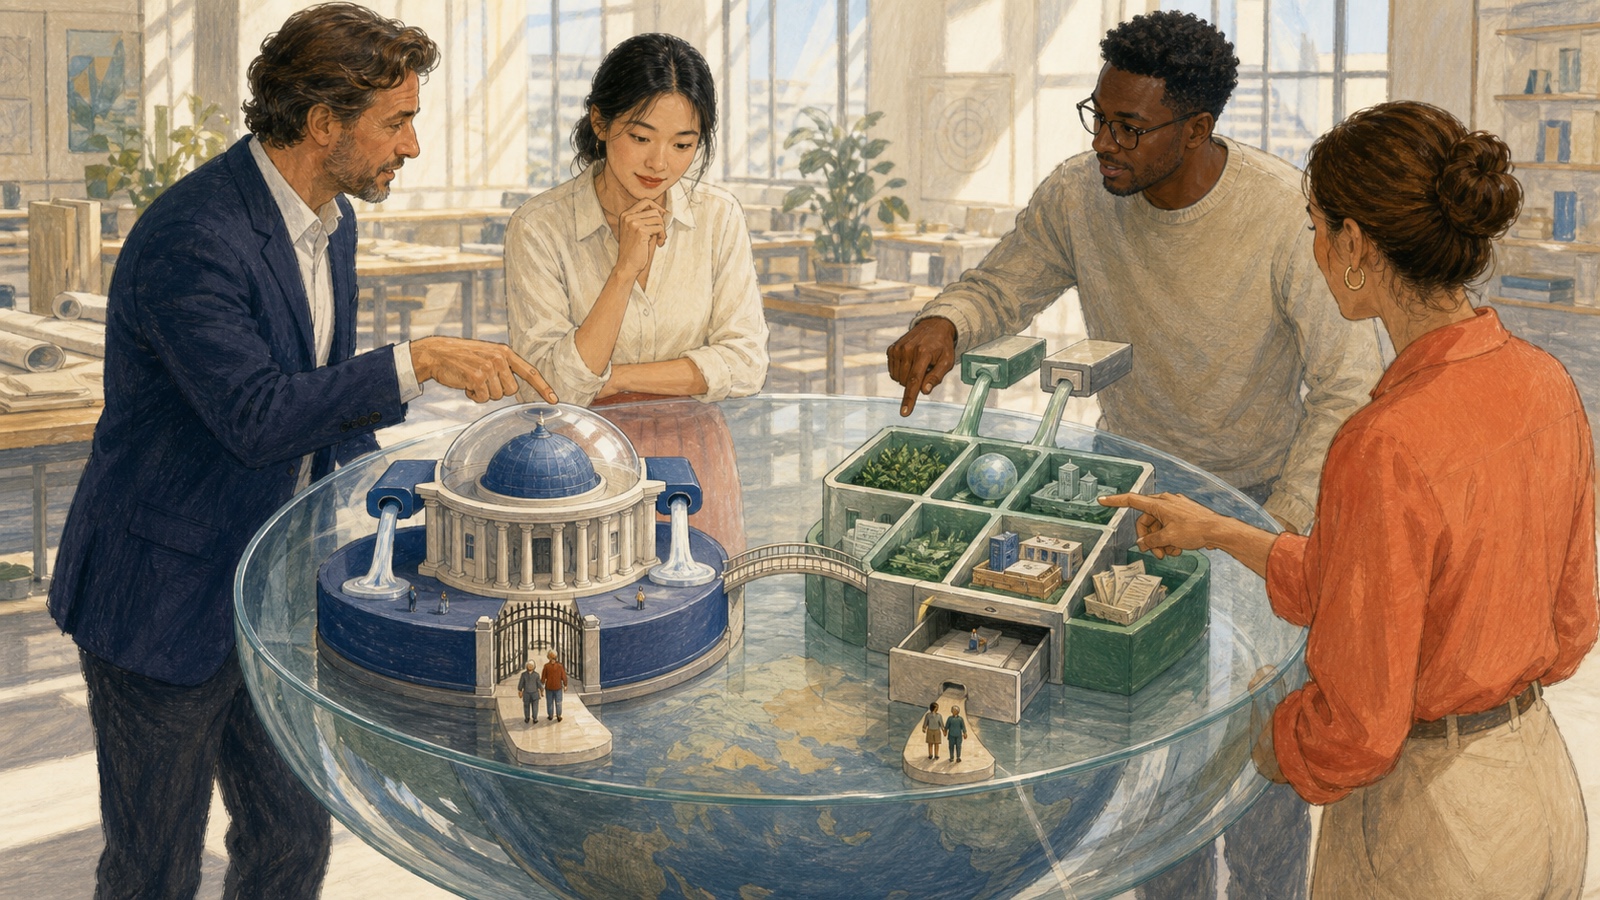
Use a Responsibility Map
Define responsibilities before launch and revisit them when vendors or countries change.
Employer or plan sponsor
Own the benefits objective, covered population, contribution philosophy, approvals, vendor oversight and escalation process. Confirm that the arrangement fits the workforce and applicable requirements.
Payroll provider
Perform the services stated in the contract, such as calculating configured deductions, producing files and reporting payroll data. Document cutoffs, corrections and rejected transactions.
Pension provider or administrator
Administer the agreed plan, maintain participant and contribution records, provide statements and disclosures, support investments and withdrawals, and report exceptions within its contracted role.
Local legal, tax and employment advisers
Assess country-specific requirements and material changes. Their role is especially important where mandatory schemes, worker classification, tax treatment or cross-border data transfers are involved.
HR, finance and security teams
Maintain employee and plan data, approve funding, reconcile costs, control access and monitor operational and security risks.
Review Each Country Before Launch
A global policy does not create one universal legal outcome. Before adding employees in a country, review:
- Mandatory public, occupational or employer-sponsored retirement arrangements
- Worker classification and employing entity
- Eligibility, enrollment and waiting periods
- Employer and employee contribution requirements
- Tax treatment of contributions, investment growth and distributions
- Funding, custody, investment and licensing rules
- Participant documents, language and disclosure requirements
- Payroll reporting, remittance and filing mechanics
- Privacy, cybersecurity and cross-border data-transfer requirements
- Termination, vesting, withdrawal, death and country-move events
Within the EU and associated countries, social-security coordination rules help determine which national legislation applies to a mobile worker. The European Commission notes that, as a general rule, a person is subject to the legislation of the country where they work, with specific rules for cross-border and posted workers. This coordination is separate from any supplemental retirement plan.
Control the Full Contribution Lifecycle
A deduction appearing in payroll does not prove that the correct amount reached the correct participant account. Reconcile the complete cycle:
- Approved employee election and employer contribution rule
- Eligibility and effective date in the benefits record
- Payroll instruction and calculated deduction
- Provider submission and accepted participant record
- Cash funding and settlement
- Allocation to the participant account
- Correction of rejected, late or mismatched items
Use a stable employee identifier, defined fields, ownership and cutoffs. Reconcile counts and amounts every cycle. Keep evidence of approvals, submissions, exceptions and corrections.
For the wider systems design, see Global Payroll and Benefits Integration: A Cross-Border HR Stack.
Country Moves Need a Separate Review
When an employee relocates, do not simply update the address and continue the same deduction. Confirm the new employing entity, payroll, applicable mandatory schemes, eligibility, tax treatment, data handling and status of accumulated savings.
Document whether the employee remains in the plan, joins a different arrangement, stops contributing or requires additional disclosures. Communicate the outcome and any required action before the next payroll cutoff where practical.
Evaluate the Provider’s Actual Scope
Ask a global payroll or retirement vendor specific questions:
- Which countries and worker types are supported under contract?
- Which plan, payroll and compliance responsibilities belong to the vendor?
- Who maintains local requirements and who approves rule changes?
- How are eligibility, deductions and employer contributions configured and tested?
- How are rejected files, late funding and corrections handled?
- What evidence, audit logs and reports are available?
- Which subprocessors receive employee or financial data?
- How can the employer export records or transition to another provider?
Separate sales language from contractual responsibility. A platform described as “compliant” may still require the employer to obtain advice, approve rules and monitor execution.
Where an International Pension Plan Fits
An international pension plan can give an employer a consistent retirement framework for defined international populations. It may improve portability and administration compared with unrelated local arrangements. It does not automatically replace mandatory national schemes or create identical tax results everywhere.
Employers should document whether the plan is supplemental, who is eligible, how contributions work, what happens after a move and which local obligations remain. Learn more about Redii’s international pension plan.
How Redii Connects Benefits and Payroll Operations
Redii supports centralized benefits administration and international retirement benefits. Employers can manage plan and participant information while connecting payroll and provider workflows through defined records and controls.
Explore Redii Benefits Administration or request a demonstration.
Authoritative References
- OECD Core Principles of Private Pension Regulation
- European Commission: Which social-security rules apply?
- IRS Publication 15: Employer’s Tax Guide
Retirement, payroll, employment, tax, social-security, privacy and financial-services requirements vary by jurisdiction and arrangement. Employers should obtain advice for the countries, workers and plans involved.
Frequently Asked Questions
Does a global payroll provider manage retirement-plan compliance?
Not automatically. Payroll may calculate deductions, transmit files or support local statutory processes, but the employer must confirm the provider’s contracted scope and assign responsibility for plan design, eligibility, governance, disclosures, funding and country-specific review.
What should an employer review before offering retirement benefits in a new country?
Review mandatory schemes, worker classification, eligibility, tax treatment, contribution and funding rules, disclosures, investments, data handling, payroll mechanics and the effect of employee moves or termination.
Can an international pension plan replace local mandatory schemes?
Not by default. An international plan may supplement local arrangements or serve defined populations, but employers need country-specific analysis to determine whether local participation remains mandatory.
How should payroll and pension contributions be reconciled?
Reconcile the employee election and employer rule to payroll instructions, deductions, provider submissions, accepted records, cash settlement and the participant account. Investigate rejected, late or mismatched items before the next cycle.